


Photoresist Market Outlook: Technological Advancements and Industry Developments
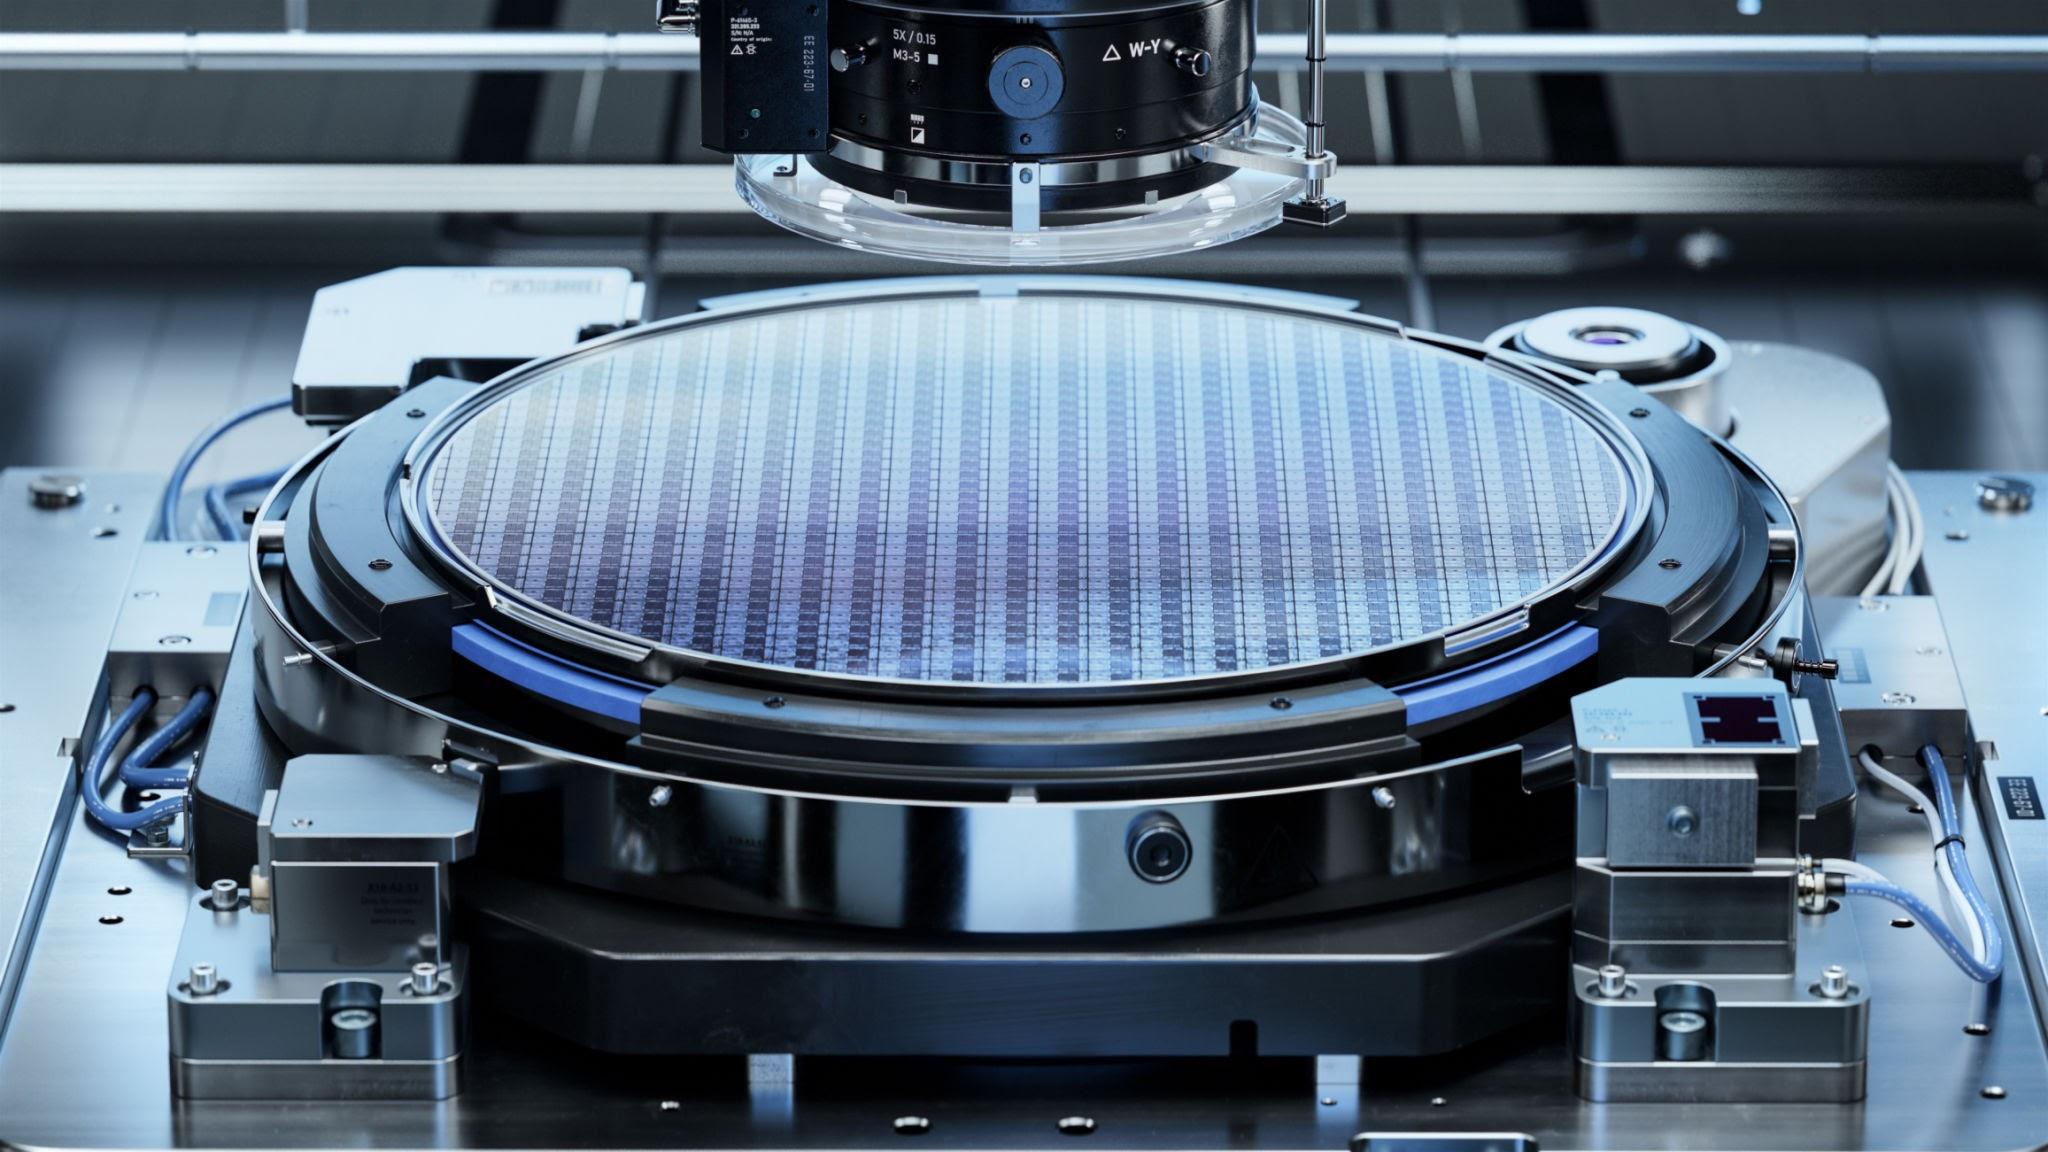
Predicting the trajectory of advanced microelectronics requires a comprehensive examination of the anticipated economic variables, capital expenditure cycles, and technological adoption rates that shape the semiconductor industry. Through a detailed Photoresist Market forecast, industry analysts, venture capitalists, and corporate strategists can identify emerging opportunities and potential bottlenecks over the coming decade. As fabrication plants increasingly adopt multi-patterning techniques and transition toward high-numerical-aperture EUV systems, the consumption patterns for specialized photoresists are projected to undergo significant shifts. This predictive outlook encompasses not only unit volume expansions across established nodes like mature 28-nanometer technologies but also the steep adoption curve of leading-edge 3-nanometer and 2-nanometer architectures. Furthermore, supply chain dynamics, raw material availability, and geopolitical trade policies heavily influence these long-term projections, requiring stakeholders to maintain agile procurement strategies and diversified sourcing networks. By closely monitoring these macroeconomic and technological indicators, semiconductor manufacturers can optimize their capital allocation, align their research pipelines with upcoming industry standards, and secure a resilient operational footprint in a highly competitive global marketplace.
In tandem with quantitative forecasting, strategic planning within the microelectronics sector must account for the rapid pace of innovation in lithography equipment and the corresponding demands placed on chemical suppliers. As wafer fabrication facilities become more automated and reliant on real-time data analytics, the integration of advanced photoresists must be synchronized with precision dispensing systems and stringent contamination control protocols. Industry roundtables and collaborative forums frequently emphasize that long-term success depends on proactive engagement between chemical developers and equipment manufacturers to co-design solutions for upcoming lithographic nodes. This collaborative ecosystem helps mitigate risks associated with pattern collapse, outgassing, and sub-optimal adhesion on complex multi-layer substrates. Ultimately, navigating the future of lithographic materials demands a holistic understanding of how technological breakthroughs intersect with market demand, ensuring that the semiconductor supply chain remains robust, scalable, and capable of supporting the next generation of computing power and electronic devices.
Frequently Asked Questions
What key variables do analysts consider when projecting long-term trends in semiconductor lithography materials? Analysts evaluate factors such as global wafer fab capacity additions, the transition timeline for advanced EUV and high-NA EUV lithography nodes, semiconductor end-market demands in automotive and consumer electronics, and capital expenditure trends among major foundry operators.
How do geopolitical factors and supply chain localization efforts influence the availability of advanced photoresist materials? Geopolitical trade policies and regional semiconductor incentives encourage localized manufacturing and dual-sourcing strategies. This shifts supply chain networks, prompting chemical suppliers to establish regional production facilities and distribution hubs closer to major foundry clusters to ensure uninterrupted material delivery.

 English
 Arabic
 French
 Spanish
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek
