


Credit Cleanup Mistakes That Keep Your Score Stuck and What to Do Instead
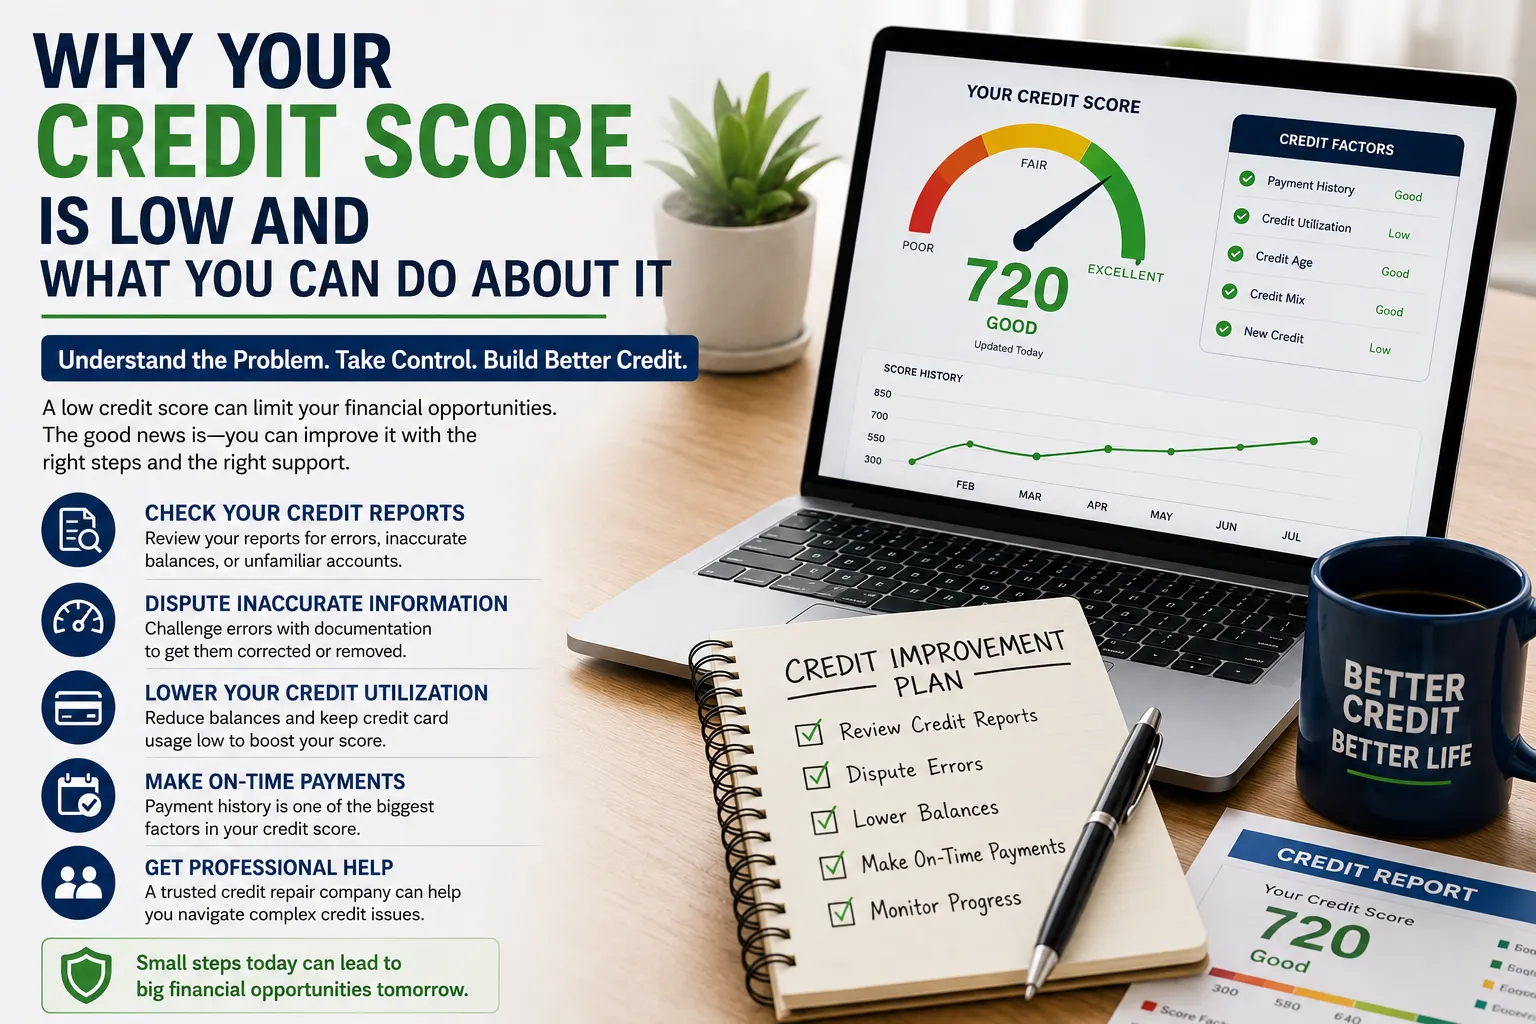
Trying to improve your credit score can be frustrating when you are making an effort but seeing little progress. You may be paying bills, checking your credit report, and trying to reduce debt, yet your score may remain lower than expected. In many cases, the problem is not a lack of effort. It is that the wrong credit issues are being addressed first.
Effective credit cleanup starts with understanding what is actually appearing on your credit reports. A high balance, inaccurate account information, missed payment, collection account, or unnecessary credit application can affect your overall credit profile in different ways.
Instead of searching for a quick credit score increase, focus on identifying the problems you can legitimately address and building financial habits that support long-term improvement.
What Does Credit Cleanup Actually Mean?
Credit cleanup is the process of reviewing your credit information, identifying potential inaccuracies, organizing outstanding financial obligations, and taking appropriate steps to improve the accuracy and overall health of your credit profile.
It does not mean removing every negative account.
Accurate negative information may remain on a credit report for the applicable reporting period. A responsible approach focuses on correcting information that is inaccurate, incomplete, or otherwise questionable rather than trying to erase legitimate financial history.
This distinction is important because understanding the difference between a credit-report error and an accurate negative account can help you avoid wasting time or money.
Mistake #1: Looking Only at Your Credit Score
A credit score can tell you where your credit profile stands at a particular point in time, but it does not explain everything behind the number.
If your score is lower than expected, review the actual credit report.
Check:
- Account balances
- Credit limits
- Payment history
- Account status
- Collection accounts
- Charge-offs
- Account opening dates
- Personal information
- Accounts you do not recognize
The report can reveal issues that a score alone cannot explain.
Once you understand the underlying information, you can create a more focused credit improvement strategy.
Mistake #2: Ignoring High Credit Card Balances
A person can make every payment on time and still have difficulty improving their credit profile if revolving balances remain high.
Credit utilization generally refers to the amount of revolving credit being used compared with the available credit limits. High utilization can be an important area to examine when your goal is to improve credit score results.
Start by creating a list of your credit cards and recording each balance and credit limit.
For example:
- Card A: $2,500 balance / $5,000 limit
- Card B: $1,800 balance / $2,000 limit
- Card C: $600 balance / $4,000 limit
This makes it easier to see where your available credit is being used most heavily.
Create a repayment plan that fits your budget. Avoid using essential household money simply to make aggressive debt payments. Credit improvement should not create a new financial crisis.
Mistake #3: Disputing Information Without Checking the Facts
Credit disputes can be appropriate when information is inaccurate, but blindly disputing every negative account is not a reliable credit cleanup strategy.
Before challenging an account, compare the reported information with your records.
Ask:
- Does this account actually belong to me?
- Is the balance correct?
- Is the payment history accurate?
- Is the account status correct?
- Does the information match my statements?
If you identify a genuine error, gather supporting documentation and follow the appropriate dispute process.
Keep copies of your correspondence and supporting evidence. Organized records can help you track what has been submitted and how the issue was addressed.
Mistake #4: Assuming Every Old Debt Should Simply Disappear
Old negative accounts can create confusion. Some consumers assume that an account is automatically inaccurate simply because it is old.
Age alone does not necessarily mean that information is incorrect.
Instead, review the account details carefully. Determine what information is being reported and whether it matches your records.
If something is inaccurate, investigate the appropriate correction or dispute process. If the information is accurate, understand that credit cleanup does not mean removing legitimate negative history simply because it is unfavorable.
The goal is an accurate report.
Mistake #5: Applying for Too Much New Credit
When someone wants to rebuild their credit, opening several new accounts may seem like a logical strategy.
However, new accounts can introduce additional monthly payments and may involve credit inquiries. If those accounts lead to higher debt, they can make an already difficult financial situation harder to manage.
Before applying for new credit, ask whether the account is necessary and whether the payment fits comfortably into your budget.
Building a healthier credit profile is more about responsible management than having as many accounts as possible.
Mistake #6: Forgetting About the Budget Behind the Credit Problem
Credit problems often have a financial cause.
If your credit card balances repeatedly increase, simply paying them down without changing the underlying spending pattern may lead to the same problem later.
Review your monthly income and expenses. Identify recurring costs, discretionary purchases, debt payments, and unexpected expenses.
Then create a realistic spending plan.
An emergency savings fund can also be useful because unexpected expenses are one reason consumers may rely heavily on credit cards. Even small, consistent savings can provide another financial resource when an emergency occurs.
When Should You Consider a Credit Repair Consultant?
Some people are comfortable handling their credit reports independently. Others may find the process confusing, particularly when several accounts or reporting issues are involved.
A credit repair consultant may help explain credit report information, identify potential areas of concern, organize documentation, and provide general guidance about appropriate credit improvement steps.
Before working with a consultant, research the provider carefully.
Ask about the services provided, fees, agreement terms, cancellation policies, and what you are expected to do yourself.
Avoid providers that promise instant results or guarantee a specific credit score. Credit improvement depends on individual circumstances and ongoing financial behavior.
What a Credit Repair Consultant Should Help You Understand
Professional guidance should make your financial situation clearer.
A consultant may help you understand terms such as credit utilization, payment history, collection accounts, revolving credit, installment accounts, and credit inquiries.
They may also help you organize a plan for reviewing your reports and addressing legitimate inaccuracies.
However, professional guidance should not encourage false information or unrealistic expectations.
If an account is accurate, a responsible approach should not involve creating a false dispute simply because the account is damaging to your score.
Create a Practical Credit Cleanup Checklist
If you do not know where to start, use a simple checklist.
1. Review
Read your credit reports carefully and identify every account that may require attention.
2. Verify
Compare questionable information with your financial records.
3. Document
Gather statements, payment records, correspondence, and other relevant evidence.
4. Address
Use appropriate procedures to challenge genuine inaccuracies.
5. Reduce
Create a realistic plan for lowering excessive revolving debt.
6. Maintain
Make payments consistently and avoid unnecessary new borrowing.
This process keeps credit cleanup organized and prevents you from trying to solve everything simultaneously.
How to Measure Credit Improvement
Do not judge your progress only by your score.
A healthier credit profile may involve several improvements, such as lower revolving balances, fewer missed payments, corrected inaccurate information, and better control over monthly debt.
Track these changes over time.
For example, if your credit card balances are steadily declining and your payment history remains current, you are addressing important parts of your financial situation even if your score has not changed dramatically yet.
Credit scoring models can also differ, so the number you see may not always be identical to the score a lender uses.
Give Your Credit Plan Time to Work
One of the biggest sources of frustration is expecting immediate results.
Creditors report information periodically, and changes may not appear on a credit report immediately. Building a stronger payment history also requires consistency over time.
Instead of checking your score every day, review your credit information periodically and focus on the actions you can control.
Ask yourself:
- Are my balances going down?
- Are payments being made on time?
- Have I addressed legitimate errors?
- Am I avoiding unnecessary debt?
- Is my budget becoming more manageable?
These questions provide a more useful picture of progress.
When Professional Credit Support May Be Useful
If your credit reports contain multiple inaccuracies, collection accounts, high balances, or complicated account histories, professional guidance may make the process easier to organize.
For readers researching their options, credit repair and credit cleanup services can be used as an external resource when learning about professional assistance. You can also provide a link to professional credit repair guidance on your website for readers who want additional information.
The important point is to research any provider carefully and understand exactly what services are being offered.
Credit Cleanup Is About Accuracy and Better Habits
A successful credit cleanup strategy is not about finding a way to make negative information disappear overnight. It is about understanding your credit reports, correcting legitimate inaccuracies, controlling debt, maintaining timely payments, and making financial decisions that support your long-term goals.
If your credit score is stuck, start by looking beyond the number. Find the specific issues affecting your profile and address them in a logical order.
A credit repair consultant can provide organization and education when the process becomes complicated, but lasting improvement also depends on your own financial habits.
The more clearly you understand your credit profile, the easier it becomes to make informed decisions. With accurate information, a realistic debt strategy, consistent payments, and patience, credit cleanup can become a manageable financial process rather than an overwhelming one.

 English
 Arabic
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek
