


Iron and Steel Slag Market Competitive Analysis and Top Companies
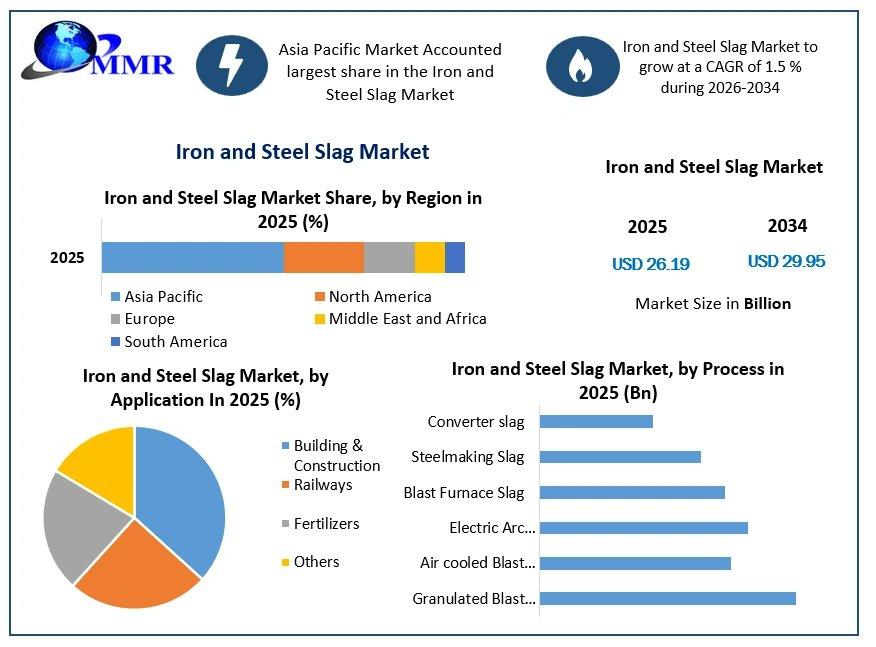
Iron and Steel Slag Market to Reach USD 29.95 Billion by 2034, Driven by Sustainable Construction
The Iron and Steel Slag Market is witnessing steady growth as industries increasingly focus on sustainable construction, industrial waste recycling, and resource efficiency. According to Maximize Market Research, the market was valued at USD 26.19 billion in 2025 and is projected to reach nearly USD 29.95 billion by 2034, expanding at a compound annual growth rate (CAGR) of 1.5% during the forecast period from 2026 to 2034. Rising infrastructure investments, demand for alternative construction materials, and growing interest in reducing industrial waste are supporting the market's long-term development.
Iron and Steel Slag Market Estimation and Growth Drivers
Iron and steel slag is a byproduct generated during iron and steel manufacturing. Depending on its production process and physical properties, it can be processed for applications such as cement production, road construction, railway infrastructure, and other industrial uses. Its potential to replace selected conventional construction materials makes it increasingly important for resource-efficient manufacturing and infrastructure development.
The market's projected increase from USD 26.19 billion in 2025 to USD 29.95 billion in 2034 reflects consistent demand across established and emerging economies. Expanding residential and commercial construction, transportation infrastructure projects, and urban development are important growth drivers. Processed slag can serve as an aggregate in suitable construction applications, while granulated blast furnace slag can be used as a supplementary cementitious material in appropriate cement and concrete formulations.
Environmental considerations are also creating opportunities. Reusing steelmaking byproducts can reduce landfill disposal and support circular-economy objectives. Improved processing technologies, metal recovery, and quality-control systems may increase the commercial value of slag. However, market expansion could be constrained by fluctuations in steel production, transportation costs, competition from conventional aggregates and other substitutes, and the need to meet environmental and product-quality requirements.
Receive a Free Sample Copy Instantly : https://www.maximizemarketresearch.com/request-sample/63603/
United States Market: Latest Trends and Investment in 2025
The United States demonstrated growing interest in industrial byproduct recovery and steelmaking efficiency in 2025. In September 2025, United States Steel Corporation announced plans for an approximately USD 100 million slag recycler at its Edgar Thomson Plant in Braddock, Pennsylvania, as part of its modernization program supported by Nippon Steel's investment commitments. The proposed facility is intended to recover value from steelmaking byproducts, including materials that can be used in cement production, while reducing waste sent to landfills. Construction was expected to begin in 2026, subject to the necessary approvals. The announcement highlights an important market trend: steel producers are increasingly considering dedicated recycling infrastructure to improve resource utilization and create additional revenue streams. Continued infrastructure development and demand for recycled construction materials may provide further opportunities for slag processors and technology providers.
Iron and Steel Slag Market Segmentation: Leading Application
By application, the building and construction segment is expected to dominate the Iron and Steel Slag Market during the forecast period. Demand is supported by the increasing use of processed slag in road construction, cement manufacturing, concrete applications, and infrastructure development. Governments and construction companies are seeking durable, cost-effective materials that can help reduce dependence on natural aggregates and improve industrial resource utilization.
Growing investment in highways, railway networks, commercial buildings, and residential developments is expected to reinforce this segment's position. The use of granulated blast furnace slag in suitable cement formulations also creates opportunities to reduce clinker requirements and associated emissions. Consistent material quality, appropriate processing, and compliance with construction standards will remain essential to wider adoption.
Competitive Analysis: Leading Companies
Competition in the global Iron and Steel Slag Market is shaped by steel production capacity, slag-processing expertise, recycling infrastructure, technological capabilities, and access to construction-material customers. Leading industry participants include the following companies:
- Nippon Steel Corporation: Nippon Steel is strengthening its steelmaking operations and resource efficiency through investments in modernization and operational improvements. Its partnership with U.S. Steel has also brought additional attention to slag recycling, including the proposed USD 100 million recycler at the Edgar Thomson Plant announced in 2025.
- Steel Authority of India Limited (SAIL): SAIL's integrated steelmaking operations generate opportunities to recover and reuse industrial byproducts. Continued improvements in material handling, resource recovery, and sustainable manufacturing can support more efficient slag utilization in infrastructure and construction applications.
- Edw. C. Levy Co.: The company specializes in industrial material processing, steel mill services, and recycling. Its expertise in processing steelmaking byproducts and recovering reusable materials positions it to benefit from increasing demand for value-added slag products.
- Stein: Stein provides services and technologies associated with steel industry operations and byproduct management. Improvements in material handling, processing efficiency, and resource recovery can help support the broader adoption of recycled industrial materials.
- JFE Steel Corporation: JFE Steel is focusing on technological development and improvements in manufacturing efficiency as the steel industry moves toward lower-emission production. Advances in byproduct utilization, slag processing, and resource circulation could strengthen the commercial value of its steelmaking residues.
Other significant participants include ArcelorMittal, Tata Steel, NLMK, Harsco Corporation, POSCO, TMS International, and JSW Steel. Market participants are expected to compete through recycling investments, operational efficiency, product quality, and partnerships with construction-material manufacturers. Individual company market shares are not specified in the available market overview.
Regional Analysis: Key Country Markets
United States: Infrastructure investment, road construction, and industrial recycling initiatives are supporting demand for processed slag. Investment in dedicated recycling facilities may increase material recovery and improve the availability of secondary construction materials. Environmental compliance and dust-control requirements remain important considerations.
United Kingdom: Infrastructure renewal, construction activity, and decarbonization objectives provide opportunities for slag-based construction materials. The use of suitable industrial byproducts can support resource efficiency and reduce reliance on virgin raw materials when technical and regulatory requirements are satisfied.
Germany: Germany's established steel industry and emphasis on circular-economy practices create opportunities for industrial byproduct recovery. Demand for sustainable construction materials and efforts to improve manufacturing efficiency may encourage greater use of processed slag.
France: Infrastructure modernization, sustainable building practices, and initiatives to reduce construction-related environmental impacts offer opportunities for slag-based products. Adoption depends on material performance, regulatory acceptance, and demand from cement and construction companies.
Japan: Japan's advanced steelmaking industry and focus on resource efficiency support slag recovery and reuse. Steel producers can improve the value of byproducts through processing innovation and applications in construction and infrastructure.
China: China's substantial steelmaking capacity, urban development, and extensive infrastructure requirements support slag generation and potential utilization. Investment in recycling systems and demand for construction materials provide opportunities for market participants.
At the global level, Asia Pacific held the dominant regional position in 2025, supported by industrialization, urbanization, and construction activity. Specific country-level market shares for the countries discussed above are not stated in the available market overview.
Key Players in the Iron and Steel Slag Market
- Nippon Steel Corporation
- Steel Authority of India Limited
- Edw. C. Levy Co.
- Stein
- JFE Steel Corporation
- ArcelorMittal
- Tata Steel
- NLMK
- Harsco Corporation
- POSCO
- TMS International
- JSW Steel
Why This Market Matters Now
The Iron and Steel Slag Market matters because it connects steel manufacturing with sustainable construction and industrial resource recovery. As infrastructure requirements increase and manufacturers seek better waste-management practices, slag can become a valuable secondary resource rather than a disposal burden.
The projected growth to USD 29.95 billion by 2034 reflects opportunities for steel producers, recycling companies, cement manufacturers, and construction-material suppliers. Investment in advanced processing, improved quality control, metal recovery, and environmentally responsible operations could strengthen the market's development. Nevertheless, successful commercialization will depend on consistent product performance, competitive costs, and compliance with applicable environmental standards.
Explore More Related Reports
Air Pollution Control Systems Market https://www.maximizemarketresearch.com/market-report/global-air-pollution-control-systems-market/20592/
Global Cytokinins Market https://www.maximizemarketresearch.com/market-report/global-cytokinins-market/91394/
About Maximize Market Research
Maximize Market Research Pvt. Ltd. (MMR) is a global market research and consulting company that provides reliable, data-focused, and practical business insights. The firm serves a wide range of industries, including healthcare, pharmaceuticals, technology, automotive, electronics, chemicals, personal care, and consumer goods. Through market forecasts, competitive analysis, and strategic consulting, MMR helps organizations understand changing market conditions, identify growth opportunities, and make informed business decisions for long-term success.
Contact Us
Maximize Market Research Pvt. Ltd.
2nd Floor, Navale IT Park Phase 3
Pune Bangalore Highway, Narhe
Pune, Maharashtra 411041, India
Phone: +91 9607365656
Email: sales@maximizemarketresearch.com

 English
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek
