


Europe’s Natural Gas Power Sector and the Path to Lower Emissions
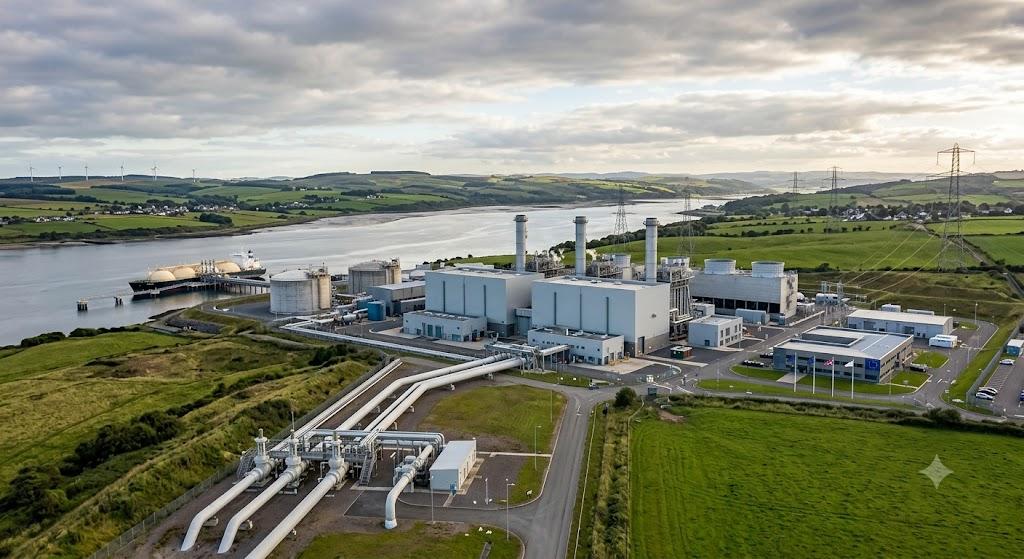
Investment Opportunities in Europe’s Natural Gas Generation Sector
Investment in European gas-fired generation is becoming more selective. Renewable capacity additions, electricity demand growth, changing fuel routes, and tighter climate policies are reshaping the economics of existing plants and proposed projects. Investors must assess not only whether a facility can generate electricity, but also when it will be dispatched, which services it can provide, and how long its business model remains compatible with policy.
The asset base includes modern combined-cycle stations, older thermal plants, and fast-start turbines serving peak and balancing needs. Each has a different risk profile. Efficient facilities may retain advantages in markets where gas sets the marginal electricity price, while older plants can struggle with maintenance costs and low running hours. Location is equally important: proximity to demand, fuel infrastructure, and constrained transmission corridors can influence strategic value.
A thorough Europe Natural Gas Power Generation Market Size assessment should define its scope carefully. Installed capacity, annual electricity production, plant investment, fuel consumption, and service revenues measure different aspects of the sector. Capacity figures alone cannot show whether assets are profitable or heavily utilised. Investors should also distinguish announced capacity from projects that have secured permits, financing, construction contracts, and grid connections.
Revenue opportunities extend beyond wholesale electricity. Depending on local market design, plants may receive capacity payments, provide balancing reserves, or support voltage and frequency services. These revenue streams can help compensate for declining energy sales, but their durability depends on procurement rules and competition. Batteries, hydro assets, flexible demand, and interconnectors may compete for the same services, potentially reducing returns as markets mature.
Capital allocation should begin with scenario analysis. Fuel-price volatility, carbon allowance costs, interest rates, electricity demand, renewable deployment, and changes to capacity mechanisms can all alter project economics. A plant that appears attractive under high utilisation may become uneconomic if dispatch hours fall sharply. Sensitivity analysis should test conservative price spreads, delayed infrastructure, unexpected maintenance, and early retirement requirements.
Existing plants may offer opportunities for operational upgrades. Turbine refurbishment, heat-rate improvements, predictive maintenance, advanced control systems, and better outage planning can improve performance without requiring a wholly new facility. However, upgrade decisions should be measured against remaining useful life and expected market revenues. Spending heavily on an asset with limited future utilisation can destroy value even when the engineering case is sound.
New-build proposals face a higher evidentiary bar in many markets. Developers need credible forecasts of system adequacy, a clear route to fuel supply, acceptable emissions performance, community support, and alignment with national energy plans. Hydrogen readiness may be presented as a future option, but investors should verify what conversion requires, whether suitable fuel will be available, and who bears the cost. Carbon capture likewise depends on transport, storage, energy penalties, and durable policy support.
Supply-chain considerations matter as well. Turbine manufacturers, engineering contractors, control-system vendors, and maintenance providers can benefit from plant life-extension and flexibility upgrades. Yet equipment lead times, specialist labour availability, and service-contract terms influence project schedules and costs. Investors should examine supplier concentration and warranty conditions rather than relying only on headline capital expenditure.
Environmental and regulatory liabilities require careful diligence. Direct carbon emissions, methane leakage in the fuel chain, water use, local air pollution, and decommissioning obligations can affect costs and public acceptance. Reporting assumptions should be transparent, particularly when comparing gas generation with storage or renewable alternatives. Transition plans need measurable milestones rather than broad statements about future technology.
The most resilient investment strategy is selective and evidence-led. Attractive assets are likely to combine competitive efficiency, reliable fuel access, useful system location, and diversified revenue potential. Others may be better candidates for limited maintenance or retirement. Plant-level data should guide capital allocation and risk management across Europe’s changing electricity system. Strong due diligence remains essential for long-term investors and operators across markets today.

 English
 Arabic
 French
 Spanish
 Portuguese
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek
